11th CommerceFinancial AccountsHSC Projects
Journalizing of Household Transactions for a Month
INTRODUCTION:
A journal entry is an act of keeping or making records of any transactions, either Economic or non-economic. In this project, we will be discussing the journalizing of household transactions for a month. Negotiations are recorded in an accounting journal that shows a firm’s debit and credit balances. The journal entry can contain several recordings, each of which is either a debit or a credit. The entire of the debits must equal the entire of the credits, or the journal entry is taken into account unbalanced. Journal entries can record unique items or recurring items like depreciation or bond amortization. In accounting software, journal entries are frequently entered using an independent module from accounts payable, which often has its sub-ledger, which affects the overall ledger. As a result, journal entries directly change the account balances on the whole ledger. An accurately cataloged journal entry includes the accurate date, an amount which will be debited, an amount which will be credited, details of Negotiations, and select reference number.AIMS AND OBJECTIVES:
This project aims at journalizing of household transactions for a month. There are essential objectives for this project. They are given below. Objectives:- To understand journal entry
- To know the importance of journals in accounts
- To follow the household transactions every month
- To see the role played by journal entry in daily households
- To ascertain any doubts regarding the journalizing of household transactions
METHOD AND METHODOLOGY:
The method used to gather the required information on the project is an internet survey method that falls under the secondary data collection method. The Internet has extensive knowledge on this subject. It has a vast collection of data on the journal entry. The survey for this project has unveiled information that is covered within major few points. They are listed below and explained in a detailed report of the project.- What is journaling entry?
- The purpose of the journal entry
- Rules of journalizing
- Journalized household transactions for a month
DETAIL REPORT OF PROJECT:
What is journaling entry?
- Personal accounts contain all those accounts which are associated with an individual, business, firm, etc. There also are subtypes of a private account. For example, in Mohan’s statement, Apple ltd. Account etc. Capital account. Dr. the receiver. Cr. the giver.
- Real accounts contain all those accounts which are associated with assets. Intangible assets also are considered as Real Accounts — for example, factory and raw material account, etc. Dr. what’s comes in. Cr. what’s goes out.
- Nominal accounts contain all those accounts which are associated with expenses, losses, Income, and Gains — for example, Rent account, wages account, etc Dr. are all expenses and losses. Cr. are all income and gains.
The purpose of a journal entry
Rules of journalizing
- The date column is supposed to record the date of the transaction.
- The second column is supposed to mark the accounts to be debited and credited.
- The third column is supposed to record the number of the ledger, where the entries are posted.
- during this column, we write the amount to be debited against Dr.
- during this column, we write the amount to be credited against Cr.
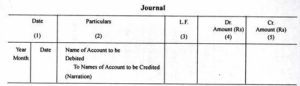 In the second column, within brackets, a quick explanation of the transaction is written, which is understood as narration. The golden rules to recollect are:
- Debit the receiver and Credit the giver.
- The debit is what comes in, and credit is what goes out.
- Debit all the expenses or losses and credit all the incomes, gains, or profits.
Journalized household transactions for a month.
| Cash brought in by the proprietor as capital Rs. 60000 Cash Account Debit 60, 000 Proprietor’s capital Account Credit 60,000 |
| Goods purchased on credit from Malang Rs. 4,000 Purchase account debit 4000 Malang account credit 4000 |
| Furniture purchased for cash Rs. 14000 Furniture Account Debit 14000 Cash Account Credit 14000 |
| Goods sold on credit to Daksh Rs. 2000 Daksh Account Debit 2000 Sale Account Credit 2000 |
| Goods purchased for cash Rs. 6000 Purchase account debit 6000 Cash account credit 6000 |
| Goods sold for cash Rs. 4000 Cash account debit 4000 Sale account credit 4000 |
| Rent paid for the shop to landlord 6000 Rent Account Debit 6000 Cash Account Credit 6000 |
| The commission received in cash 2000 Cash Account Debit 2000 Commission Account Credit 2000 |
| Money deposited into bank 30000 Bank Account Debit 30000 Cash Account Credit 30000 Cash is withdrawn from bank for office use Rs. 22000 Cash Account Debit 2200 Bank Account Credit 2200 |
| Cash has drawn by the proprietor from the business for personal use Rs. 5000 Drawing Account Debit 5000 Cash Account Credit 5000 |
| Goods are given as charity Rs. 1000 Charity Account Debit 1000 Purchase Account Credit 1000 |
| Bad Debts are written off Rs. 500 Bad Debt Account Debit 500 Debtor Account Credit 500 |
| Bad debts recovered in cash Rs. 300 Cash Account Debit 300 Bad Debts Recovered Account Credit 300 |
| Depreciation on fixed assets Rs. 650 Depreciation Account Debit 650 Fixed Asset Account Credit 650 |
| Goods are given as free samples Rs. 1000 Advertising Account Debit 1000 Purchase Account Credit 1000 |
| Interest allowed on capital Rs. 2000 Interest on capital Account Debit 2000 Capital Account Credit 2000 |
| Interest charged on drawings Rs. 200 Drawing Account Debit 200 Interest on drawing account Credit 200 |
| Bank charges or interest charged by bank Rs. 270 Bank charge Account Debit 270 Bank account Credit 270 |
| Goods lost by fire Rs. 100 Loss by Fire Account Debit 100 Purchase Account Credit 100 |
| A loan is taken Rs. 60000 Cash Account Debit 60000 Lender’s loan Account Credit 60000 |
| Interest paid on loan. Rs. 1500 Interest on loan Account Debit 1500 Cash Account Credit 1500 |
| Interest on loan due but not paid in cash is Rs. 550 Interest on loan Account Debit 550 Loan or Creditor Account 550 |
| The investment purchased is Rs. 30,000 Investment Account Debit 30000 Cash Account Credit 30000 |
| Cash stolen from the office is Rs. 5000 Loss by Theft Account Debit 5000 Cash Account Credit 5000 |
| Cash paid to a creditor in full settlement. Malang Account Debit 5000 Cash Account Credit 2500 Discount Received Account Credit 500 |
| Cash received from a debtor in full settlement. Cash Account Debit 3000 Discount Allowed Account Debit 300 Daksh Account Credit 2700 |
ANALYSIS OF DATA:
After analyzing the gathered data, The Journal is a Book of Chief Entry. It’s otherwise referred to as the Book of Original Entry. These entries are then affixed from the journal into the ledger. As such, the accounting is understood because of the Principal Book or the most Book. The ledger is otherwise referred to as the Book of last Entry. Hence, the journal is recognized as Subsidiary Record or Subsidiary Book. Journalizing is an act of recording the debit and credit aspects of a business transaction in journal, alongside evidence of the sale, referred to as narration. The information recorded within the journal, which certainly is a symbol or evidence within the court of law. It provides the bottom for ledger posting and also for cross-checking of entries posted. It maintains the detailed record of transactions within the sort of narration, written immediately after passing the entrance; hence it provides a highlight of the sale done. Because the transactions are recorded in chronological order, it’s useful for straightforward reference within the future.CONCLUSION:
To successfully conclude my findings, Every business carries various transactions throughout the day. Some sales are similar; many are different. Hence, it’s impossible to stay all the journalizing process in mind without recording it. Of these transactions are essential and thus can’t be avoided or omitted. So, to avoid any mistake or omission, these transactions are recorded in books. Journalizing is the traditional sort of keeping track of happenings within the organization.DISCUSSION:
The discussion with my guidance counselor on this project, it is revealed: Journal entries supply documentation of all business transactions in one place on the time and date basis. All sales are recorded on the idea of receipts or bills, so we will check the authenticity of every journal entries with their laws. There’s a minimum chance to avoid any particular transaction because in journal transactions are recorded date basis. Accountant writes every journal entry’s narration bellow of that journal entry, so other auditors can know what the rationale of that journal entry is. In journal entries, every transaction is recorded after an in-depth analysis of two accounts on the idea of a double-entry bookkeeping system, so there’s minimal chance of mistake in the journal.SUGGESTION:
After discussing this project with friends and peers, they have individual opinions and recommendations. They are given below: There should be activities and practical to teach students about journal entries in college. There should be a seminar for the uneducated public for free. This should be taught at the school level so children would be able to have proper knowledge about accounting early on in their life.ACKNOWLEDGMENT:
My profound gratitude to all the faculty members of the Department, for their timely assistance and encouragement throughout my research work. I duly acknowledge the encouragement and support from the research scholars in the Department, and all my colleagues and friends. It gives me immense pleasure to take the opportunity to all the people who are directly or indirectly involved in the completion of my project based on Journalizing household tractions for a month. With deep reverence, I offer my deepest gratitude _____, without whom this project could not have been fulfilled. Lastly, I thank Almighty, my parents, family members, friends, and teachers for their constant encouragement and support, without which this project would not be possible. Name of School/CollegeBIBLIOGRAPHY / REFERENCE:
- https://www.thebalancecareers.com/definition-of-a-journal-entry-3515176
- http://www.yourarticlelibrary.com/accounting/journal/rules-of-journalising-with-specimen/50007
- https://tallygame.com/accounting/what-is-journalising/
- https://en.wikipedia.org/wiki/Journal_entry
Common search variants this project covers
Related searches this project answers: what is journalising, goods used for household journal entry, goods use for household journal entry, journalise transactions, good use for household journal entry, journalizing business transactions, journalizing transactions in accounting, goods issued for household purpose journal entry, household journal, proprietor used goods for household purposes journal entry, journalizing transaction, what is journalizing, what is journal discuss the rules of journalising, journalizing accounting transactions, cash taken for household purpose journal entry, 30 transactions of accounts for project class 11, journalized transactions, journal entry for goods used for household.
Click to rate this post!
[Total: 19 Average: 4.9]