Government Budget And Its Components
INTRODUCTION:
In the modern world, every go government aims at maximizing the welfare of its country. It requires a number of infrastructural, economics and welfare activities. All these activities require huge expenditure to be incurred. This requires appropriate planning and policy of the solution to all these problems is ‘Budget’. A budget is a document containing detailed programmes and policies of action for the given fiscal year.MEANING:
The government budget is an annual statement, showing item wise estimates of receipts and expenditures shown in the budget are not the actual figures, but the estimated values for the coming year. The fiscal year is taken from 1st April to 31st March.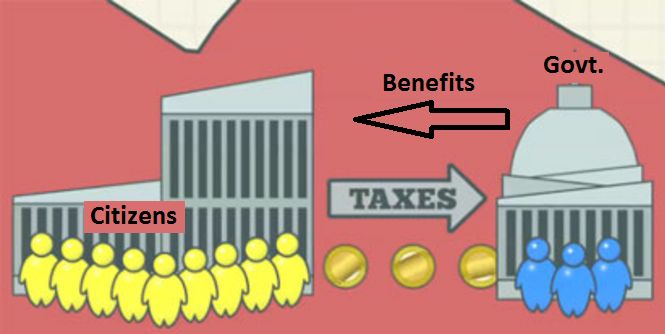 Important Points of Govt. Budget:
- Budget is prepared by the Government of all level i.e. Central Government. State Government and Local Government, prepares its respective annual budget. However, we will restrict our studies to the budget of Central Government known as Union Budget.
- Estimated expenditures and receipts are planned as per the objectives of the government.
- In India, Budget is presented in parliament on such a day as the President may direct By convention it is presented on the last working day of February each year.
- It is required to be approved by the parliament before it can be implemented.
OBJECTIVES:
Government prepares the budget for fulfilling certain objectives. These objectives are the direct outcome of Government economic, social and political policies. The various objectives of the Government budget, etc. Reallocation of Resources: Through the budgetary policy, the Government aims to reallocate resources in accordance with the economic and social priorities of the country.- Tax Concessions or Subsidies: To encourage investment, the Government can give tax to Producers. For example, the Government discourages the production of harmful by providing subsidies.
- Directly producing goods and services: If the private sector does not take an interest, the Government can directly undertake the production.
COMPONENTS OF BUDGET:
Two major components of the Budget are: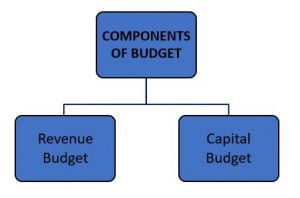
Revenue Budget:
- The receipt must not create a liability for the Government. For example, taxes levied by the Government are revenue receipts as they do not create any liability. However, any amount borrowed by the Government is not a revenue receipt as it causes an increase in the liability in terms of repayment of borrowings.
- The receipt must not cause a decrease in the assets. For example, receipts from the sale of shares of a public enterprise is not a revenue receipt as it leads to a reduction in assets of the Government.
Capital Budget:
- Tax Revenue:
- Non-Tax Revenue:
- Fees: The Government provides a variety of services for which fees have to be paid. Example- fees paid for registration of property, births, deaths, etc.
- Fines and Penalties: Fines and penalties are imposed by the Government for not following the rules and regulations.
- Profits from public sector enterprises: Many enterprises are owned and managed by the Government. The profits received from them is an important source of non-tax revenue. For example, In India, the Indian Railways, Oil and Natural Gas Commission, Air India, Indian Airlines, etc. are owned by the Government of India.
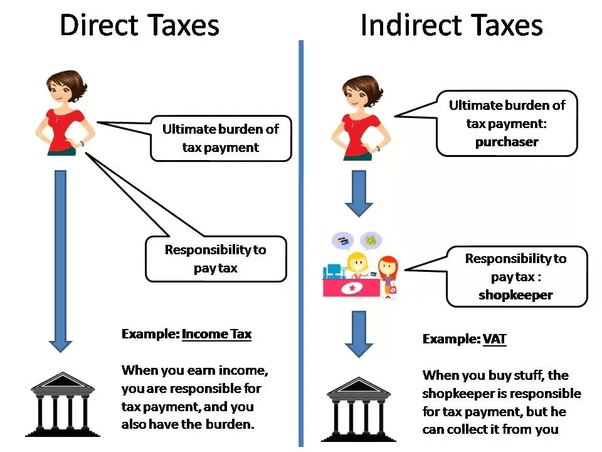
- Direct Taxes:
- Indirect Taxes:
- Items categorized as Direct and Indirect Tax: It is a direct tax as its impact and incidence lie on the same person. It is a direct line on the same person.
- Value Added Tax: It is an indirect tax as its impact and incidence lie on two different people, its burden can be shifted.
- Service Tax: It is an indirect tax as its impact and incidence lie on a different person.
- Excise Duty: It is a direct tax as its impact and incidence lie on the same person.
- Non-Tax Revenue: Non-Tax Revenue refers to receipts of the Government from all sources other than those of tax receipts. The main sources of non-tax revenues are:
- Interest: The government receives interest on loans given by it to State Government, Union Territories, Private Enterprises and General Public.
- Fees: Fees refer to charge imposed by Government to cover the cost of recurring services provided by it. Court fees, registration fees, import fees, etc. are some examples of fees.
- License Fees: It is a payment charged by the Government to grant permission of something’s license fees paid for permission of keeping a gun or to obtain it.
- Times and Penalties: They refer to that payment which is imposed on lawbreakers, fine for jumping light for non-payment of tax. The latter is imposed to generate revenue.
- Escheats: It refers to the claim of the Government on the property of a person who dies without leaving behind a will.
- Gifts and Grants: The government receives gifts and grants from foreign Government and International Organisations. Sometimes, individuals and companies money to the Government received during a national crisis such as war, food, etc.
- Forfeitures: These are in the form if penalties which are imposed by the court for non-compliance of others contract, etc.
- Special Assessment: It refers to the payment made by Owners of these properties whose value has appreciated due to developmental activities of the Government expenditure is recovered from owners.
- The receipts must create a liability for the Government Borrowings are capital receipts as they Government. However, tax received is not a capital receipt as it does not result in the creation of any liability.
- The receipts must cause a decrease in the assets receipts from the scale of a share of public enterprises is a capital receipt as it leads to a reduction in assets of the Government.
- Borrowings:
- Government Open Market
- Reserve Bank of India
- Foreign Government
- International Institutions
- Borrowings are capitals receipts as they create a liability for the Government.
- Recovery of Loans:
- Other Receipts:
- Loan from the Word Bank: It is a capital receipt as it creates liability for this Government.
- Corporation Tax: It is revenue receipt as it neither creates any liability nor reduces any asset.
- Grants received from world bank: It is a revenue receipt as it neither creates nor reduces the asset of the Government.
- Profits of Public Sector Undertakings: It is a revenue receipt as it neither creates reduces asset of the Government.
- The scale of a Public Sector Undertaking: It is a capital receipt as it reduces assets of the Government.
- Foreign Aid against Earthquake Victims: It is revenue receipt as it neither creates nor reduces any asset of the Government.
- Dividends on Investments Made Government: It is revenue receipt as it neither creates nor reduces any asset of the Government.
- Borrowings from Public: It is a capital receipt as it creates liability.
- Fees of Government College: It is revenue receipt as it neither creates any nor reduces any asset of the Government.
BUDGET EXPENDITURE:
 Budget Expenditure refers to the estimated expenditure of the Government during a given fiscal year. The budget expenditure can be broadly categorized as:
- Revenue Expenditure:
- It is recurring in nature.
- It is incurred on the normal functioning of the Government.
- The Expenditure must not create an asset of the Government payment of salaries or pension is revenue expenditure as it does not create an asset. Metro is not a revenue expenditure as it leads to the creation of an asset.
- It is non-recurring in nature.
- It adds to the capital stock of the Economy and increases its productively through expenditure on long periods like Metro or Flyovers.
- Examples: Loan to State and Union Territories expenditure on building roads, flyovers, etc.
- Subsidies: It is a revenue expenditure as it neither creates an asset nor reduces any of the Government.
- Defense capital equipment purchased from Germany. It is a capital expenditure as it increases asset of the government
- Grants are given to State Governments. It is a revenue expenditure as it neither creates any asset nor any reduces any of the government.
- Construction of School buildings. It is a capital expenditure as it increases asset of the Government.
- Expenditure incurred on administrative is a revenue expenditure as it neither creates nor reduces any liability of the Government.
- Repayment of Loans: It is a capital expenditure as it reduces the liability of the Government.
- Expenditure on building a bridge. It is a capital expenditure as it increases asset of the Government.
- Payment of salaries to the staff of Government. It is a revenue expenditure as it neither creates any asset nor reduces any of the Government.
- Purchase of 20 Cranes for the flyovers. It is a capital expenditure as it increases asset of the Government.
- Plan Expenditure: Plan Expenditure refers to the expenditure that is incurred on the Programmes detailed in the current five-year plan. For example Expenditure on Agriculture and allied activities, irrigation, energy, transport, etc. (i) Projects covered under the Central Plans. (ii) Central Assistance for State and Union Territory.
- Non-Plan Expenditure: Non-Plan Expenditure refers to the expenditure other than the expenditure related to the current five-year plan.
- Plan expenditure is spent on current development and investment outlays non-plan expenditure is spent on the asset of the Government.
- Plan expenditures arise only when the plans provide for such expenditure but non-plan expenditure is a must for every economy and the Government cannot escape from it.
- Development expenditure directly contributes to the development of the economy, whereas non-development expenditure does not contribute directly to the development but it lubricates the wheels of economic development.
- Development expenditure is productive in nature as it adds to the flow of goods and services whereas non-development expenditure is not covered with the productivity of working clash.
- An Expenditure is a development expenditure if it directly adds to the flow of goods and services.
- Revenue Deficit.
- Fiscal Deficit.
- Primary Deficit.
- It indicates the inability of the Government to meet its regular and recurring expenditure in the proposed budget.
- It implies that the government is discussing i.e. Government is using up saving of other sectors of the economy to finance its expenditures.
- It also implies that the government has to make up this deficit from capital receipts i.e. through borrowings or reduces the assets through.
- Use of capital receipts for meeting the extra consumption expenditure leads to an inflationary situation in the economy.
- A high revenue deficit gives a warning signal to the government to curtail its expenditure.
- Reduce Expenditure: Government should take serious steps to reduce its expenditure and avoid unproductive or unnecessary expenditure.
- Borrowings:
- Deficit Financing:
 The government may borrow from RBI against its securities to meet the fiscal deficit. RBI issues new currency for this purpose. Primary Deficit & Implications: It indicates how much of the Government Borrowings are going to meet the expense. It indicates payment the difference between fiscal deficit and primary deficit shows the amount of interest payment on the borrowings made in the past. In India, interest payment has considerably increased in recent years. High-interest payments on past borrowings have greatly increased the fiscal deficit. To reduce the fiscal deficit interest payment should be reduced through repayment of loans as early as possible. Reasons for Selection of this Topic:
- To have an understanding of Government administration.
- To know about the sources of Government Expenditure + Government’s Revenue.
- To know about how Government meets its deficit.
- To have an acquaintance of Government objectives, capital receipts, capital expenditure, revenue receipts, and revenue expenditure.
ACKNOWLEDGMENT:
I would like to convey my heartfelt thanks to Mr./Mrs. Aman Khurana my Economics teacher who always gave me valuable suggestions and guidance during the completion of these projects. He/She has been a source of inspiration & helpful hand in the completion of this project. My project has been successful only because of his/her guidance. Name of the Student: Your Name Roll No. allotted by CBSE :CERTIFICATE:
This is to certify that Mr./Mrs. Manminder Kaur of class XII – C of Guru Nanab International Sr. Sec. Public School has completed his/her project file under my supervision. He/She has taken my supervision and has taken proper care and shown utmost sincerity in the completion of the project. I certify that this project is up to my expectations and as per the guidance issued by CBSE. ___________________ (P.G.T Commerce) (Signature)DOWNLOAD PDF OF THE PROJECT
Password: hscprojects.com
Common search variants this project covers
Related searches this project answers: components of budget, components of government budget, component of budget, components of budget class 12, government budget and its components, government budget and its components project class 12 pdf, what are the components of government budget, components of budget images, government budget and its components introduction, structure of government budget, budget components, components of government budget class 12, what are the components of budget, government budget, government budget meaning and its components, component of budgeting, component of government budget, government budget components, government budget and its components project class 12, government budget class 12, budget and its components, components of government, reallocation of resources in government budget, government budget and its components pictures, components of the budget.
More search queries this project answers
Related searches this project answers: main components of government budget, components of government budget images, component of a budget, components of buget, government budget and its components project pdf, revenue budget, what are the components of government budget class 12, deficit financing meaning, government budget and it's components, what is government budget class 12, parts of budget, components of a budget, two parts of budget, government budget project class 12, components of the government budget, component of government, components of budgeting, components of govt budget, government budget class 12 project, project on government budget and its components, introduction of government budget and its components, government budget and its component, components of union budget, composition of budget, discuss the components of government budget.
More search queries this project answers
Related searches this project answers: budget component, two components of budget, budget divided into 2 parts, parts of government, government budget and its components project images, what is government budget explain its major components, budget composition, what is non tax revenue with example, what are the components of a budget, meaning and components of government budget, government budget and its components project file class 12, structure of government budget and its components, components of government budget india, elements of budget, govt budget class 12, meaning of government budget, class 12 economics project file on government budget and its components, main components of budget, government budget and its components pdf, government budget project file class 12, government budget and its components project class 12 ppt, what is government budget, project government budget, government budget and its components images, indirect tax examples.
More search queries this project answers
Related searches this project answers: government budget project, government budget and its components class 12, government budget and its components project, government budget meaning, national budget of india, what is budget in government, what is government budget and its components, what are the components of the government budget, non tax revenue example, two components of government budget, concept of government budget, define government budget class 12, components of government budget pictures, components of government expenditure, explain the components of government budget, goverment budget, element of budget, examples of direct and indirect tax, government budget and its structure, government budget of india, different parts of government, features of government budget class 12, difference between direct and indirect tax class 12, what are the main components of a government budget, indian government budget.
More search queries this project answers
Related searches this project answers: india government budget, government budget project pdf, government components, deficit financing, 2 parts of budget, budget receipts class 12, project file on government budget and its components, project on government budget, capital budget class 12, components of national budget, conclusion of government budget, class 12 economics project on government budget, class 12 government budget project, india govt budget, indian govt budget, important points of government budget, importance of government budget class 12, importance of government budget pdf, non tax revenue examples, objective of government budget class 12, key components of budget, indian national budget, introduction of government budget, government budget project cover page, government budget types.
More search queries this project answers
Related searches this project answers: government budget meaning in economics, government budget definition, government budget images, image form, images, image, government constituents, government expenditures, what is a government budget, what is budget in political science, the government budget and taxation, state budget article, structure of the budget, what is in budget, what is meant by government budget, what is government budgeting, what is component, what is deficit financing, picture, project on government budget class 12, pic bhej, objectives of government budget class 12 pdf, part of budget, receipts in budget, revenue and expenditure budget.
More search queries this project answers
Related searches this project answers: reallocation of resources, project on government budget class 12 pdf download, provide a picture, government budget chart, component, component of fiscal policy, class 12 economics project government budget and its components, capital receipts, chitra, components of capital budgeting, components of consumption expenditure class 12, components of budget pdf, components, components of a government budget, aspects of budgeting, budget, ans, government budget and its components project pdf class 12, 4 components of a budget, capital expenditure, capital expenditure and revenue expenditure of government, budgeting components, budget elements, budget sections, fiscal budget.
More search queries this project answers
Related searches this project answers: fiscal budget meaning, financial statement showing the expected receipts and proposed expenditure of the government in the coming financial year, examples of direct tax, examples of non tax revenue, give me photos of that, government budget breakdown, for project, fiscal policy budget, flow chart of government budget class 12, definition of government budget, describe the, define government budget, components of final expenditure, components of the national budget, elements of budgeting, example of non tax revenue, economics project on government budget, developmental and non development expenditure, difference between direct tax and indirect tax with example.
This is very good project of economics
THANK YOU SIR
Thanks for the project